×

The Standard e-Paper
Fearless, Trusted News
 The Standard Group Plc is a
multi-media organization with investments in media platforms spanning newspaper
print operations, television, radio broadcasting, digital and online services. The
Standard Group is recognized as a leading multi-media house in Kenya with a key
influence in matters of national and international interest.

Audio By Vocalize
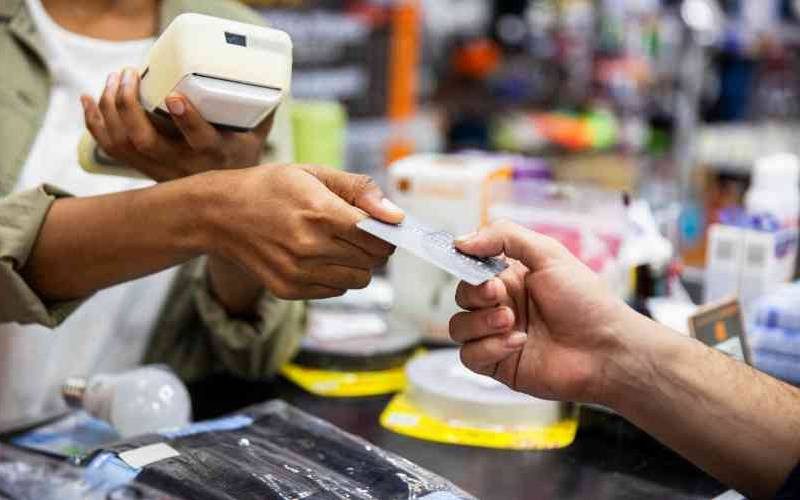
Africa’s digital economy is often discussed through the products people see - mobile money, digital banking, e-commerce platforms, fintech applications and online marketplaces. They are important parts of the transformation. But beneath them sits a less visible layer that may prove just as important: payments infrastructure.
The question for Africa is no longer simply whether people can make digital payments. It is whether the systems supporting those payments can become part of a more efficient and connected economy.
That distinction is important. A digital payment creates a record of a transaction.
When payment infrastructure is connected to the wider systems used by businesses and governments, that transaction can become part of a broader flow of information.
This has implications beyond convenience. For businesses, digital payments can make transactions easier to track and reconcile.
For governments, connected payment systems can support more efficient administrative processes and better visibility.
For consumers, digital payment infrastructure can make participation in formal economic activity easier.
The value therefore lies partly in what happens around the transaction. Africa’s economies are diverse. Many businesses continue to operate informally, while consumers use a mix of cash and digital payment channels.
Connectivity and financial access also vary considerably between and within countries.
Digital payments cannot solve these challenges by themselves.
They can, however, form part of the infrastructure through which economies become more connected. Consider the relationship between payments and government.
When government processes depend on disconnected systems, a transaction may have to pass through several administrative steps before it can be reconciled and reported.
Each additional manual process creates another opportunity for delay, error or incomplete information. Digitising the payment is one step. Connecting the payment to the wider process is another.
This is where Africa’s payments infrastructure becomes important.
The GSMA State of the Industry Report on Mobile Money 2026 reports that mobile money services processed more than $2 trillion (Sh260 billion) in transactions globally during 2025, a 23 per cent increase from 2024.
Stay informed. Subscribe to our newsletter
But the focus should move from individual payment products to the systems that allow payments to work across broader economic processes. That requires interoperability, appropriate regulation, security and trust. It also requires a willingness to design systems around the realities of African markets.
There is no single African digital economy.
Kenya’s payments ecosystem has developed differently from Tanzania’s. South Sudan faces a different set of institutional and economic conditions. The appropriate infrastructure therefore needs to reflect local realities while remaining capable of connecting to wider financial systems.
This is one reason African technology companies have an important role to play.
Companies operating across multiple markets can bring experience from different environments while adapting implementation to local requirements.
The objective should not be to copy one country’s model into another market.
It should be to understand which principles travel and which need to be redesigned.
The economic implications are significant.
Greater visibility over transactions can support better business management.
More efficient payment processes can reduce administrative friction. Digital records can contribute to better information for decision-making. And easier access to formal payment systems can support wider participation in the formal economy.
None of these outcomes is automatic. They depend on infrastructure, adoption, regulation, trust and how systems are designed and implemented. That is why Africa’s payments conversation needs to become more ambitious. The question is no longer simply whether a consumer can pay digitally at a shop, or whether a business can receive money through a mobile application.
The bigger question is what happens when payments become part of the infrastructure connecting consumers, businesses, governments and financial institutions.
That is where the main opportunity lies. Africa’s digital economy will not be built only through the applications people see on their phones. It will also be built through the infrastructure operating behind them.
The payments layer may be less visible. But its economic importance is becoming harder to ignore.
-The writer is the Global Chief Strategy Officer at CapitalPay International
Subscribe to our newsletter and stay updated on the latest developments and special offers!
 join